
How Restoration Reports Support Insurance Claims

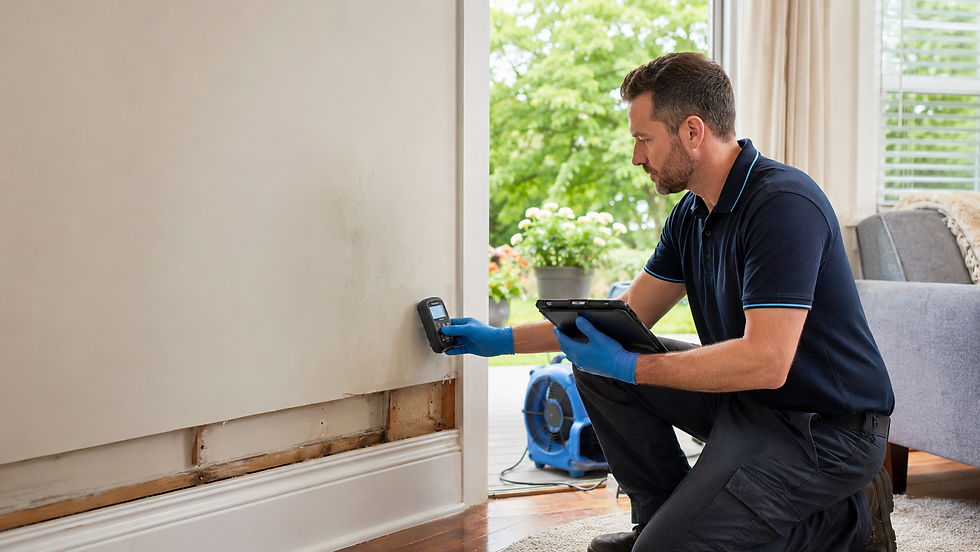
After property damage, there are usually two urgent problems. The first is stopping the loss from getting worse. The second is proving what happened.
A restoration report helps connect those two problems. It organizes the condition of the property, the apparent cause of the damage, the emergency response, the affected materials, and the work completed. That record gives the owner, restoration contractor, property manager, and insurance adjuster a common set of facts to review.
The report does not guarantee that a claim will be approved. Coverage still depends on the policy wording, the cause of loss, exclusions, endorsements, deductibles, limits, and whether policy conditions were followed. What a good report can do is reduce confusion and preserve evidence before the site changes.
What is a restoration report?
A restoration report is a written and visual record prepared after water, fire, smoke, storm, impact, mould, contamination, vandalism, or another property loss. The exact format varies with the incident and the professional preparing it.
A useful report normally identifies the property, the date and time of attendance, the reported discovery time, the people present, the observed conditions, the apparent source, the areas and materials affected, and the immediate actions taken.
Depending on the loss, it may also include moisture readings, equipment logs, temperature and humidity records, photographs, video, floor plans, contents lists, removal notes, disposal records, contractor invoices, repair estimates, and follow up observations.
Six ways the report can support a claim
1. It establishes a timeline
Insurance claims are easier to understand when the file shows when the damage was discovered, when it was reported, who attended, and what changed after each response step. A clear timeline can distinguish the original loss from later deterioration and show whether emergency steps were taken promptly.
2. It preserves conditions before cleanup
Water is extracted. Wet drywall is removed. Soot is cleaned. Fallen branches are cut. Contents are moved. These actions may be necessary, but they also change the evidence.
Photographs and notes taken before materials are disturbed, when it is safe to do so, can preserve the location, severity, and visible pattern of the damage. The Insurance Bureau of Canada recommends documenting damage, keeping detailed notes, assembling receipts and other records, and keeping damaged items unless they create a health hazard.
3. It defines the apparent cause and scope
The insurer must consider whether the loss falls within the policy. A report can help show where the damage began, how it travelled, and which building materials or contents were affected.
This is especially important when the difference between a sudden event and a gradual condition may affect the coverage analysis. A report should describe observations carefully and should not present an uncertain cause as a proven fact.
4. It records reasonable mitigation
Property owners are generally expected to take reasonable steps to protect the property after a loss. The response may include shutting off water, arranging emergency plumbing, placing a temporary roof covering, boarding an opening, extracting water, moving contents, or installing drying equipment.
The report should record what was done, when it was done, who authorized it, and why it was necessary. It should also distinguish emergency mitigation from permanent repairs.
5. It connects costs to the work
An invoice with one large total does not explain much. A stronger file connects labour, materials, equipment, disposal, cleaning, contents handling, testing, and repairs to the affected area and the work performed.
Daily logs, photographs, equipment records, and itemized invoices help the adjuster review whether the claimed cost is related to the reported loss.
6. It creates continuity from emergency response to repair
Several contractors may attend the same property. One stops the leak. Another removes damaged materials. Another dries the structure. Others complete electrical, roofing, environmental, or reconstruction work.
A coordinated report helps prevent gaps between these stages. It identifies completed work, remaining hazards, unresolved questions, required approvals, and the next responsible party.
What a strong restoration file should contain
The property address, claim number, policyholder contact, and insurer or adjuster contact.
The reported date and time of loss, discovery, notification, and attendance.
The weather and site conditions when relevant.
Wide view and close view photographs with clear room or area labels.
A factual description of the apparent source and the route of damage.
A list of affected rooms, structures, finishes, systems, and contents.
Moisture, temperature, humidity, air quality, or other readings when relevant and taken by qualified people.
Emergency actions, authorizations, equipment placement, and daily progress.
Materials cleaned, removed, stored, discarded, or left for further assessment.
Itemized estimates, invoices, receipts, and contractor information.
Outstanding deficiencies, safety concerns, and recommended next steps.
Communication records with the owner, adjuster, occupants, contractors, and other decision makers.
What a restoration report cannot do
A report cannot rewrite the policy, remove an exclusion, prove a cause that was never properly investigated, or guarantee payment. It should not exaggerate damage or blend old maintenance problems into a new claim.
The best report is accurate, organized, dated, and limited to what the writer observed, measured, completed, or received from a clearly identified source.
Take ACTION after property damage
Protect people from immediate hazards.
Contact the insurer or broker as soon as practical and ask what emergency work is authorized.
Document the site before cleanup when it is safe to do so.
Keep damaged property unless the insurer directs otherwise or it creates a health or safety hazard.
Keep receipts, estimates, photographs, reports, and communication in one claim file.
Ask contractors to separate emergency mitigation, restoration, and unrelated maintenance in their scope and invoices.
12 Gates Property Services can inspect and document damaged properties, coordinate site access and qualified contractors, organize photographs and records, monitor restoration progress, and report outstanding property risks.
Book a consultation to discuss property documentation and restoration coordination. Visit 12GatesPS.com and book your free 15-minute consultation.
12 GATES PROPERTY SERVICES
PROTECTING PROPERTIES. MINIMIZING LOSS.
This article provides general property risk management information. It is not legal advice, insurance advice, or a coverage opinion. Policies and claims vary. Confirm requirements with the insurer, broker, adjuster, and qualified legal counsel where necessary.
Frequently asked questions
Can a restoration report guarantee that an insurance claim will be approved?
No. The report can support the evidence, but coverage depends on the policy and the facts of the loss.
When should the report be started?
As soon as the site is safe to access and before important conditions are changed by cleanup or repair.
Who can prepare the report?
The file may include reports from restoration contractors, property risk professionals, plumbers, roofers, engineers, environmental consultants, electricians, and other qualified specialists. Each writer should stay within their expertise.
Sources and further reading
Insurance Bureau of Canada, severe weather claim documentation guidance: https://www.ibc.ca/news-insights/news/ibc-launches-its-virtual-camp-and-provides-insurance-information-following-hurricane-fiona-in-atlantic-canada
Financial Services Regulatory Authority of Ontario, Home Insurance Thematic Review Report: https://www.fsrao.ca/media/25821/download
General Insurance Ombud Service, Frozen Water case study: https://giocanada.org/case-studies/property-damage-frozen-water/


Comments